
OCEAN Mining has finalized a buyout of co-founder and 16-year veteran Bitcoin Core developer Luke Dashjr, concluding his equity ownership and three leadership roles within the Bitcoin mining pool.
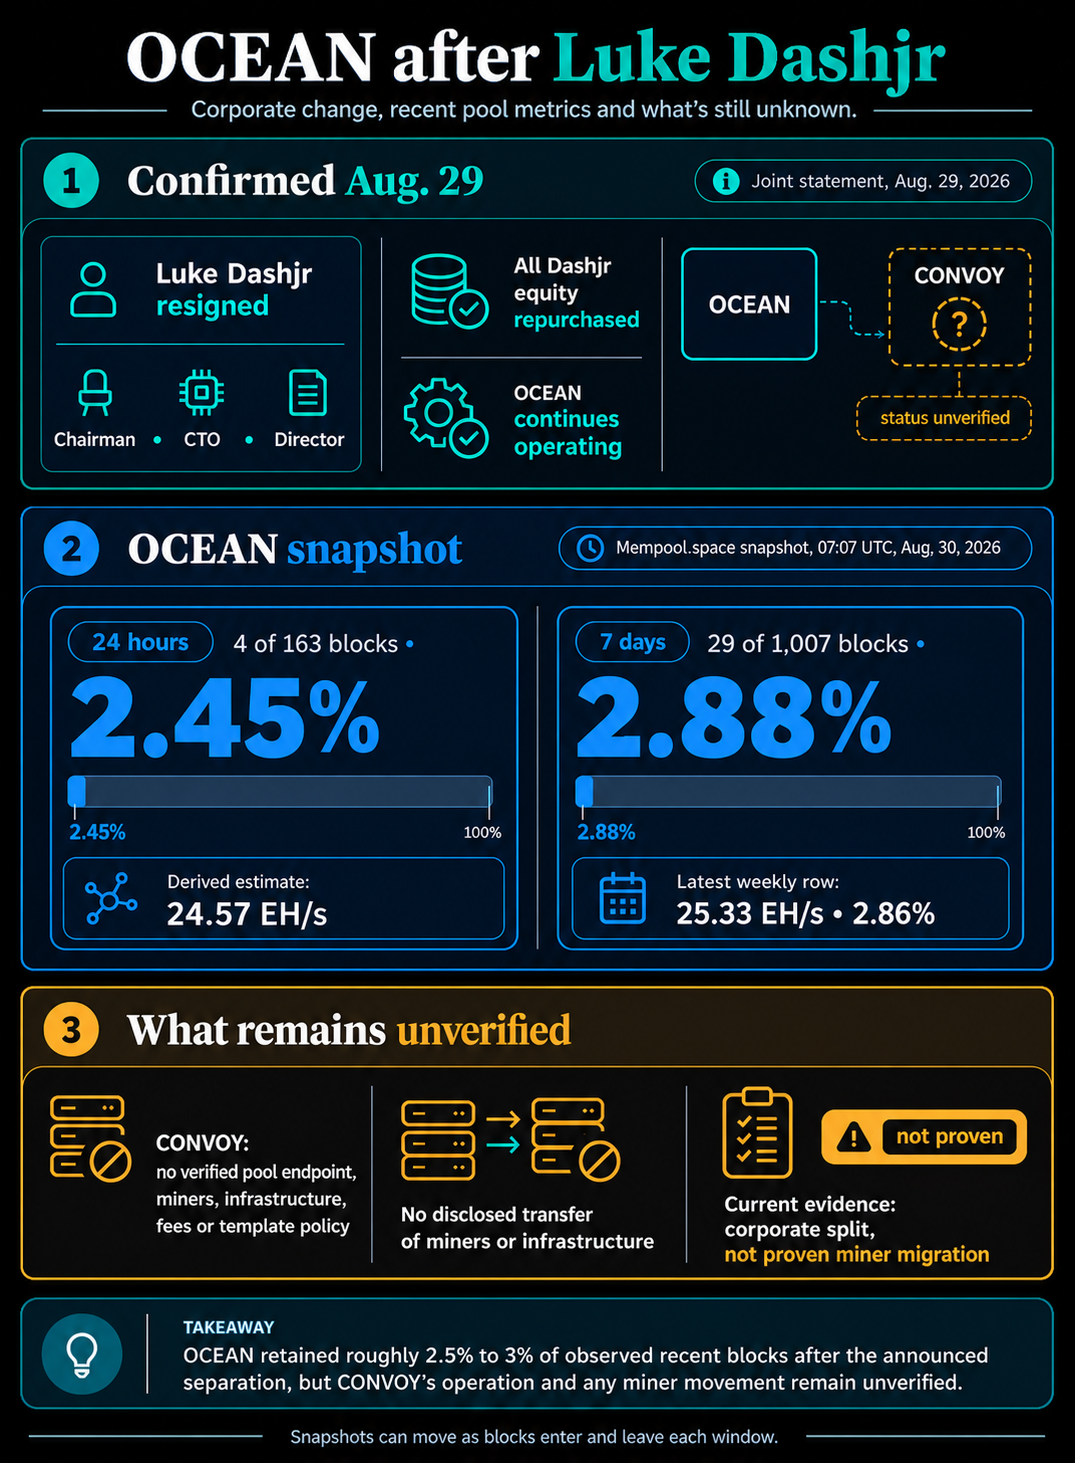
According to an Aug. 29 joint statement, Dashjr stepped down from his positions as chairman, chief technology officer, and director, while OCEAN bought back all of his shares. Holding these board, technical, and executive roles previously put him at the core of OCEAN’s decision-making regarding both governance and mining policy.
The private firm did not reveal the financial terms of the repurchase, its updated ownership distribution, or who will fill the vacant roles. OCEAN stated it will maintain operations for its non-custodial, transparent pool, whereas Dashjr plans to launch a new mining initiative called CONVOY.
At the time of reporting, CONVOY had not provided sufficient details to confirm an active pool. The public announcement and profile lacked information regarding an endpoint, codebase, participating miners, infrastructure, fee structure, or block-template policies. Furthermore, there was no indication of any infrastructure, staff—aside from Dashjr—or miners moving over from OCEAN.
OCEAN still represents a measurable share
Data from a Mempool.space snapshot taken at 07:07 UTC on Aug. 30 showed that OCEAN mined four out of the preceding 163 Bitcoin blocks, amounting to 2.45%. Multiplying this share by the network’s overall hashrate estimate yielded an approximate block-share-based calculation of 24.57 exahashes per second.
The broader timeframe showed similar metrics. Mempool.space attributed 29 out of 1,007 blocks over the trailing week to OCEAN, representing 2.88%, while its most recent weekly hashrate metric placed the pool at 25.33 EH/s, or 2.86% of the network.
Across both timeframes, OCEAN stayed inside a steady 2.5% to 3% range, meaning any departure of miners remains noticeable without letting a single block indicate a broader trend.
These metrics reflect the hashpower directed toward OCEAN instead of physical hardware owned by the business. Additionally, a trailing 24-hour window fluctuates quickly as individual blocks enter and exit the data set, turning it into a momentary snapshot rather than a permanent measure of market share.
The joint announcement noted that the parting of ways stemmed from divergent visions following recent protocol updates, though it did not explicitly cite Bitcoin Knots, BIP-110, a proof-of-work shift, or any other specific proposal as the catalyst.
In July, OCEAN launched dedicated endpoints for BIP-110 alongside no-signal options, before switching its default endpoint back to the non-BIP-110 chain on Aug. 9 while keeping both alternatives accessible. OCEAN pointed out that its DATUM framework allows participating miners to dictate block assembly. While CryptoSlate previously covered the surrounding proof-of-work conflict and blockchain split, the departure announcement did not attribute the buyout to any particular event.
Definitive proof that miners and template policies are shifting will only come from a fully operational CONVOY pool, public mining directives, or a lasting shift in OCEAN’s market share. The corporate restructuring alone does not prove such a move.

